2026 Tax Law Changes: How New Regulations Could Impact Your Investment Portfolio by Up To 15%
Anúncios
2026 Tax Law Changes: How New Regulations Could Impact Your Investment Portfolio by Up To 15%
The year 2026 looms large on the horizon for investors, marked by the potential for sweeping 2026 Tax Changes that could redefine the financial landscape. These aren’t just minor adjustments; we’re talking about fundamental shifts that could impact your investment portfolio by as much as 15% or even more, depending on your asset allocation and income levels. Understanding these impending regulatory shifts is not just prudent; it’s essential for safeguarding and growing your wealth.
Anúncios
The expiration of key provisions from the Tax Cuts and Jobs Act (TCJA) of 2017 is the primary catalyst for these anticipated changes. While the specifics are still subject to legislative debate and political maneuvering, the general direction points towards higher taxes for many, particularly high-income earners and those with significant capital gains. This article will delve into the potential implications of these 2026 Tax Changes, explore how they might affect different types of investments, and, most importantly, provide actionable strategies to help you prepare and adapt.
The Looming Sunset of TCJA Provisions: What to Expect
The Tax Cuts and Jobs Act of 2017 brought about significant changes to the U.S. tax code, including lower individual income tax rates, increased standard deductions, and various business tax reforms. However, many of these provisions were temporary, scheduled to “sunset” at the end of 2025. This means that without new legislation, the tax code will revert to its pre-TCJA state in 2026, leading to what could be substantial 2026 Tax Changes for individuals and businesses alike.
Anúncios
Individual Income Tax Rates
One of the most direct impacts will be on individual income tax rates. The seven tax brackets introduced by the TCJA are set to expire. This could mean higher marginal tax rates for many taxpayers, particularly those in the middle and upper-income brackets. For instance, the top individual income tax rate could revert from 37% to 39.6%. This increase in ordinary income tax rates will have a ripple effect on investment income that is taxed at these rates, such as interest income from bonds, short-term capital gains, and distributions from certain retirement accounts.
Standard Deduction vs. Itemized Deductions
The TCJA significantly increased the standard deduction, leading many taxpayers to opt for it rather than itemizing. In 2026, the standard deduction amounts are slated to decrease, potentially making itemizing deductions more attractive for a larger number of taxpayers. This could impact charitable giving strategies, mortgage interest deductions, and state and local tax (SALT) deductions. The SALT cap, which limits the deduction for state and local taxes to $10,000, is also set to expire. Its removal would be a boon for high-income earners in high-tax states, but its potential reinstatement or modification remains a key point of discussion.
Estate Tax Exemption
The federal estate tax exemption also saw a substantial increase under the TCJA. In 2026, this exemption is scheduled to revert to its pre-TCJA levels, adjusted for inflation. This means that a significantly lower amount of wealth can be passed on to heirs free of estate tax. For high-net-worth individuals, this particular aspect of the 2026 Tax Changes could necessitate a complete overhaul of their estate planning strategies, potentially involving more complex trusts, gifting strategies, and life insurance policies to mitigate the increased tax burden on their estates.
Other Key Individual Provisions
- Child Tax Credit: While the TCJA increased the child tax credit, its future form after 2025 is uncertain. Any changes could significantly impact families.
- Alternative Minimum Tax (AMT): The TCJA significantly curtailed the reach of the AMT. Its potential resurgence or modification could affect a broader range of taxpayers.
- Qualified Business Income (QBI) Deduction: The Section 199A deduction for qualified business income, which allows eligible pass-through entities to deduct up to 20% of their qualified business income, is also set to expire. This would impact small business owners and self-employed individuals significantly.
How 2026 Tax Changes Could Impact Your Investment Portfolio
The ripple effects of these 2026 Tax Changes will extend far beyond your annual tax return, directly influencing the after-tax returns of your investments. A 15% swing in your portfolio’s value due to taxation might sound extreme, but for certain asset classes and income brackets, it’s a very real possibility.
Capital Gains and Dividends
Currently, long-term capital gains and qualified dividends enjoy preferential tax rates, often lower than ordinary income tax rates. While these rates are not directly tied to the TCJA sunset, changes in ordinary income tax rates can create pressure to adjust capital gains rates in future legislation. If ordinary income tax rates rise, the appeal of long-term capital gains might diminish relative to other investment income. Furthermore, proposals for higher capital gains taxes, especially for high-income earners, are frequently part of broader tax reform discussions. An increase in the capital gains tax rate from, say, 20% to 25% or even higher, coupled with the 3.8% Net Investment Income Tax (NIIT), could significantly erode your investment returns.
Interest Income and Fixed-Income Investments
Interest income from bonds, savings accounts, and other fixed-income investments is generally taxed at ordinary income rates. If individual income tax rates increase in 2026, the after-tax return on these investments will decrease. This could make tax-advantaged fixed-income options, such as municipal bonds, even more attractive, potentially driving up their demand and altering their yields. Investors relying on bond income for retirement or regular cash flow will need to re-evaluate their strategies.
Real Estate Investments
Real estate investors could face multiple impacts. Changes to depreciation rules, the 1031 exchange (like-kind exchange) provisions, and capital gains taxes on property sales are all potential areas of reform. If the 1031 exchange is limited or eliminated, it would significantly impact investors who use it to defer capital gains when reinvesting in similar properties. Furthermore, any changes to the deductibility of mortgage interest or property taxes (related to the SALT cap) could affect the profitability of real estate holdings.
Retirement Accounts
While contributions to 401(k)s and traditional IRAs are typically pre-tax, distributions in retirement are taxed as ordinary income. If ordinary income tax rates rise in 2026, future withdrawals from these accounts will be subject to higher taxes. This makes Roth conversions and contributions to Roth accounts (where contributions are after-tax but qualified withdrawals are tax-free) potentially more appealing, especially for those who anticipate being in a higher tax bracket in retirement or believe tax rates will generally increase in the future. Understanding the tax implications for various retirement vehicles will be crucial for effective retirement planning.
Strategic Planning to Mitigate the Impact of 2026 Tax Changes
The prospect of significant 2026 Tax Changes can be daunting, but with proactive planning, you can mitigate negative impacts and even find new opportunities. The key is to act strategically and consider your unique financial situation.
1. Re-evaluate Your Asset Location Strategy
Asset location refers to deciding which types of investments to hold in which types of accounts (taxable, tax-deferred, or tax-exempt). With potential changes to ordinary income and capital gains rates, optimizing asset location becomes even more critical:
- Taxable Accounts: Consider holding tax-efficient investments like passively managed index funds, ETFs, and individual stocks with low turnover that generate qualified dividends or long-term capital gains.
- Tax-Deferred Accounts (e.g., 401(k), Traditional IRA): These are ideal for investments that generate ordinary income, such as bonds, REITs, and high-dividend stocks, as taxes are deferred until withdrawal.
- Tax-Exempt Accounts (e.g., Roth IRA, Roth 401(k)): These are excellent for high-growth investments, as all qualified withdrawals are tax-free, shielding you from future tax rate increases.
2. Harvest Capital Gains and Losses Strategically
Tax-loss harvesting is a well-known strategy, but tax-gain harvesting might become more relevant. If capital gains tax rates are expected to rise in 2026, consider realizing some long-term capital gains in 2025, especially if you are currently in a lower capital gains bracket. Conversely, if you anticipate lower capital gains rates in the future (perhaps due to a change in your income bracket), you might defer realizing gains. Always balance this with your overall investment strategy and market outlook.
3. Optimize Retirement Contributions and Conversions
With potential higher income tax rates in 2026, 2025 could be an opportune time for Roth conversions. Converting a traditional IRA to a Roth IRA means paying taxes on the converted amount at your current (potentially lower) ordinary income tax rate. This allows all future growth and qualified withdrawals from the Roth IRA to be tax-free. This strategy is particularly powerful if you expect to be in a higher tax bracket in retirement or if you believe overall tax rates will increase in the long term.
4. Review Your Estate Plan
Given the scheduled reduction in the estate tax exemption, high-net-worth individuals should urgently review and update their estate plans. Strategies to consider include:
- Gifting: Utilize annual gift tax exclusions and lifetime gift tax exemptions before they potentially decrease.
- Irrevocable Trusts: Establish various types of irrevocable trusts (e.g., ILITs, GRATs) to remove assets from your taxable estate.
- Charitable Giving: Explore charitable trusts and foundations to achieve philanthropic goals while potentially reducing estate taxes.
5. Consider Tax-Advantaged Investments
As tax rates rise, the appeal of tax-advantaged investments increases:
- Municipal Bonds: Interest earned on municipal bonds is generally exempt from federal income tax and often from state and local taxes if you reside in the issuing state.
- Tax-Efficient Mutual Funds/ETFs: Funds designed for tax efficiency minimize capital gains distributions.
- Opportunity Zones: Investments in Qualified Opportunity Funds offer tax deferral, reduction, and potential exemption of capital gains.
6. Business Tax Planning
For business owners, the potential expiration of the Section 199A QBI deduction is a significant concern. Business owners should consult with tax professionals to explore alternative strategies, such as restructuring, optimizing business expenses, or exploring other deductions that may still be available. Understanding how changes to corporate tax rates might also influence business decisions and investment in the private sector is also paramount.
The Broader Economic and Market Implications
Beyond the direct impact on individual portfolios, the 2026 Tax Changes could have broader economic and market implications. Higher taxes could reduce disposable income, potentially dampening consumer spending. For businesses, increased corporate taxes (if they are also part of future legislation) could affect profitability, investment, and hiring decisions. These macroeconomic shifts can, in turn, influence market performance across various sectors.
Market Volatility
Uncertainty surrounding tax policy can lead to increased market volatility. As 2026 approaches, and depending on the political climate, investors might react to proposed or enacted legislation, causing market fluctuations. Staying informed and maintaining a long-term perspective will be crucial during such periods.
Sector-Specific Impacts
Different sectors of the economy might react differently to tax changes. For example, sectors heavily reliant on consumer spending could face headwinds if disposable income decreases. Conversely, industries that benefit from government spending or those with strong international components might be less affected or even find new opportunities. Understanding these nuances can help in adjusting sector allocations within your portfolio.
The Importance of Professional Guidance
Navigating the complexities of impending 2026 Tax Changes requires more than just a cursory understanding. The interplay of various tax provisions, their potential impact on different investment vehicles, and your personal financial goals necessitates a tailored approach. This is where the expertise of a qualified financial advisor and tax professional becomes invaluable.
Why Consult a Professional?
- Personalized Assessment: A professional can analyze your specific financial situation, including your income, assets, liabilities, and long-term goals, to determine how the 2026 Tax Changes will uniquely affect you.
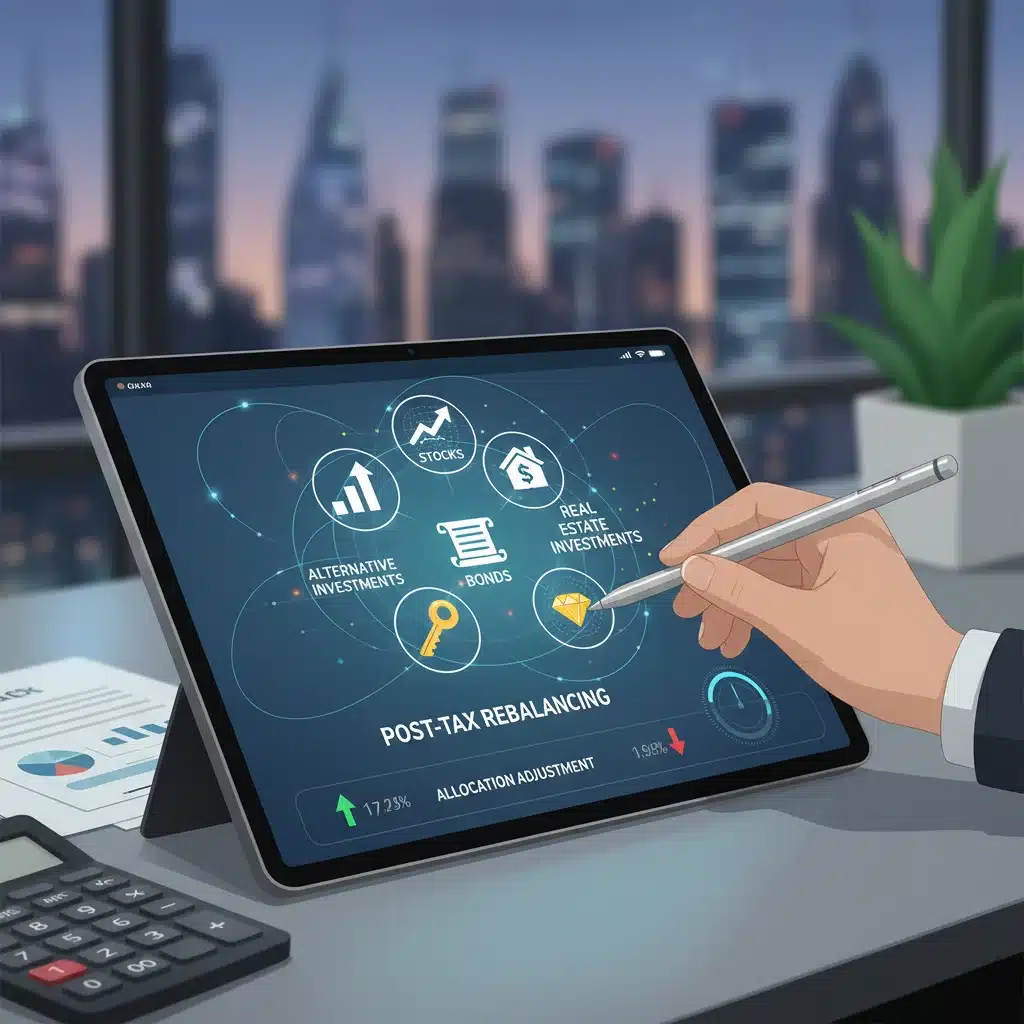
- Strategic Planning: They can help you develop a comprehensive strategy that integrates tax planning with your investment, retirement, and estate planning objectives. This might involve rebalancing your portfolio, optimizing asset location, or executing Roth conversions at the most opportune time.
- Stay Updated: Tax laws are dynamic. A professional stays abreast of legislative developments, proposed changes, and new interpretations, ensuring your plan remains compliant and optimized.
- Risk Mitigation: They can help identify potential risks associated with tax changes and implement strategies to mitigate them, protecting your wealth from unnecessary erosion.
- Opportunity Identification: Beyond mitigation, tax changes often present new opportunities. A skilled advisor can help you identify and capitalize on these to enhance your after-tax returns.
Preparing for the Unknown: A Continuous Process
While the exact nature of the 2026 Tax Changes remains somewhat fluid, the general direction points towards a more challenging tax environment for many investors. The potential for a 15% impact on your investment portfolio is not a figure to be ignored. It underscores the urgency of proactive planning and continuous adaptation.
The best approach is to view tax planning not as a one-time event but as an ongoing process. Regularly review your financial plan, stay informed about legislative developments, and maintain open communication with your financial and tax advisors. By doing so, you can position yourself to not only navigate the upcoming changes but to thrive amidst them, ensuring your investment portfolio continues to support your long-term financial aspirations.
Don’t wait until the last minute. The sooner you begin to assess the potential impact of the 2026 Tax Changes and implement strategic adjustments, the better prepared you will be to protect and grow your wealth in the evolving economic landscape.
Key Takeaways for Investors:
- Anticipate Higher Rates: Prepare for potential increases in individual income tax rates, capital gains taxes, and a reduced estate tax exemption.
- Review Asset Location: Optimize where you hold different types of investments across taxable, tax-deferred, and tax-exempt accounts.
- Consider Roth Conversions: 2025 might be an ideal window to convert traditional IRA assets to Roth IRAs.
- Update Estate Plans: High-net-worth individuals should urgently review and adjust their estate strategies.
- Seek Professional Advice: Engage with qualified financial and tax advisors to develop a personalized and robust plan.
The future of taxation is always subject to change, but by understanding the likely trajectory of the 2026 Tax Changes and taking decisive action now, you can transform potential challenges into opportunities for financial resilience and growth.